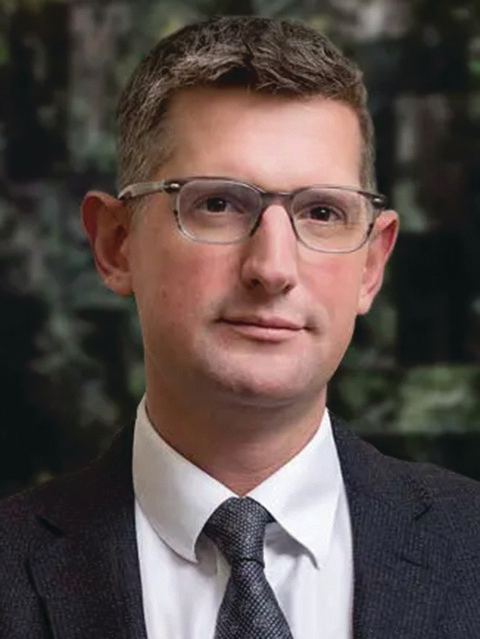
One minute with James McCredie, Partner at Macfarlanes.
What’s keeping you busy at work?
The constant changes to the carried interest rules over the last decade have kept me very busy – it is a novel experience to have just had a budget which didn’t change them again. On top of the day job, heading up our tax and reward team of 80+ people means each day brings something both taxing and rewarding.
What do you know now that you wish you’d known at the start of your career?
Not everything that is announced will happen and not everything you have to do needs doing! I have a ‘three in five’ rule – of every five things on your list only three need to be done. Unfortunately, knowing which three only comes with experience.
The same goes for technical changes: remember FATCA Passthru payments, ATAD 3 and the Common Consolidated Corporate Tax Base? Me neither.
Another thing, of course, is how quickly it goes. One minute you are a trainee trying to spell ‘SDLT’ and the next you are head of department and being asked to do a ‘one minute with’ for Tax Journal – an honour as much as it is ageing!
What caught your eye in the Budget?
The outcome of the distributions consultation is probably the biggest change for most taxpayers.
Helpfully, the Budget documents do clearly state they want to avoid unintended consequences, in particular for the private capital industry, but that is likely to mean a lot of work and consultation before we get to a final position. The fact this (pretty techy) measure made the Chancellor’s speech (alongside changes to sovereign immunity – the other big development) is perhaps a sign of how little else was changing, which in itself is something to be thankful for!
If you could make one change to tax, what would it be?
Oversimplification of a complex issue, but I would change the (mostly historic) rules which force people to move business or value outside of the UK rather than into it. For example, I would abolish the UK’s central management and control corporate residence test (at least in an investment context) and switch to a US-style test for where profits are to be taxed. Why are we forcing everyone to run these things outside the UK? To what end, except to support other jurisdictions’ service industries?
What’s topical in your world?
The big topical issue is the scope of the miscellaneous income charge following the BlueCrest, HFFX and Boston Consulting cases. It seems the test has been narrowed simply to ‘is this cash in the nature of income or reward for services?’ with no other tests attached. However, HMRC’s repeated success in this area makes one fear for less income-like scenarios. Some even-handed guidance would be useful to help both HMRC and taxpayers form some agreement as to where the line is (assuming HMRC agree that there is one...).
Finally, you might not know this about me but…
Many who know me would say I am not exactly renowned for my Zen-like approach to work interactions. However, I have recently rediscovered salmon fishing and I am comforted that there can never be a tax enquiry so frustrating, nor a corporate deal so infuriating as the Sisyphean experience of flogging a river in the rain for days while the fish ignore you. Nothing at work can touch me now. (I have already booked for next year.)
One minute with James McCredie, Partner at Macfarlanes.
What’s keeping you busy at work?
The constant changes to the carried interest rules over the last decade have kept me very busy – it is a novel experience to have just had a budget which didn’t change them again. On top of the day job, heading up our tax and reward team of 80+ people means each day brings something both taxing and rewarding.
What do you know now that you wish you’d known at the start of your career?
Not everything that is announced will happen and not everything you have to do needs doing! I have a ‘three in five’ rule – of every five things on your list only three need to be done. Unfortunately, knowing which three only comes with experience.
The same goes for technical changes: remember FATCA Passthru payments, ATAD 3 and the Common Consolidated Corporate Tax Base? Me neither.
Another thing, of course, is how quickly it goes. One minute you are a trainee trying to spell ‘SDLT’ and the next you are head of department and being asked to do a ‘one minute with’ for Tax Journal – an honour as much as it is ageing!
What caught your eye in the Budget?
The outcome of the distributions consultation is probably the biggest change for most taxpayers.
Helpfully, the Budget documents do clearly state they want to avoid unintended consequences, in particular for the private capital industry, but that is likely to mean a lot of work and consultation before we get to a final position. The fact this (pretty techy) measure made the Chancellor’s speech (alongside changes to sovereign immunity – the other big development) is perhaps a sign of how little else was changing, which in itself is something to be thankful for!
If you could make one change to tax, what would it be?
Oversimplification of a complex issue, but I would change the (mostly historic) rules which force people to move business or value outside of the UK rather than into it. For example, I would abolish the UK’s central management and control corporate residence test (at least in an investment context) and switch to a US-style test for where profits are to be taxed. Why are we forcing everyone to run these things outside the UK? To what end, except to support other jurisdictions’ service industries?
What’s topical in your world?
The big topical issue is the scope of the miscellaneous income charge following the BlueCrest, HFFX and Boston Consulting cases. It seems the test has been narrowed simply to ‘is this cash in the nature of income or reward for services?’ with no other tests attached. However, HMRC’s repeated success in this area makes one fear for less income-like scenarios. Some even-handed guidance would be useful to help both HMRC and taxpayers form some agreement as to where the line is (assuming HMRC agree that there is one...).
Finally, you might not know this about me but…
Many who know me would say I am not exactly renowned for my Zen-like approach to work interactions. However, I have recently rediscovered salmon fishing and I am comforted that there can never be a tax enquiry so frustrating, nor a corporate deal so infuriating as the Sisyphean experience of flogging a river in the rain for days while the fish ignore you. Nothing at work can touch me now. (I have already booked for next year.)