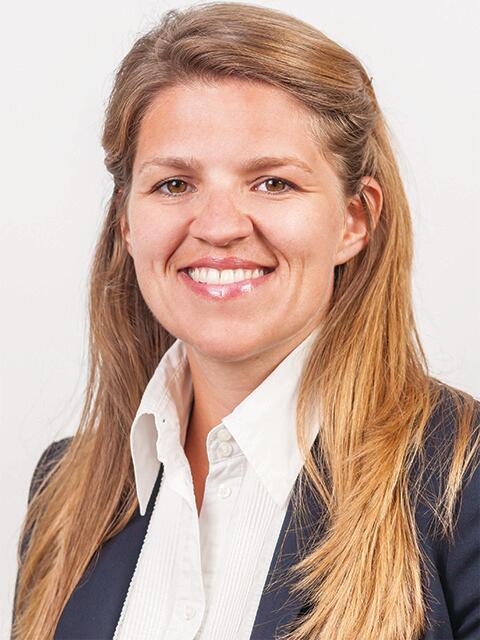
One minute with Helen Miller, Director at the Institute for Fiscal Studies.
What’s been keeping you busy at the IFS?
Our annual IFS Green Budget, published this week, which analyses the challenges and choices facing the Chancellor at the upcoming Budget. I reckon I’ve read over half a million words in the editing process!
If you could make one change to the UK tax system, what would it be?
I’d probably go for scrapping SDLT. It’s a terrible tax. A tax on housing transactions has no part to play in a modern tax system. People would be happier if they were freer to move to new homes. Growth would be higher if it was less costly to move to a new job. Of course, scrapping it would be costly. It brings in a cool £20bn each year. It’s not my place to comment on whether tax revenues should be higher or lower – that’s a political choice. But whatever the goal, stamp duty is not a good way to raise revenue.
A particularly attractive option would be to make up the revenue through a reformed council tax. This should be based on up-to-date valuations – not valuations made when I was starting school. It should be proportional to values, rather than regressive so as not to unfairly favour very valuable properties.
But now there’s a growing list of changes to the tax system. Perhaps this is why we have a tax code that’s such a mess: politicians often look at policy measures in isolation, whereas what we need is to look at the system in the round.
What do policymakers often misunderstand about how taxes actually affect people or businesses?
Policymakers often focus on tax rates, perhaps understandably because they are the most salient part of the tax system. But the tax base – the definition of what is actually being taxed – is at least as important. The misunderstanding that can arise by overlooking the tax base can, I think, be most easily seen in relation to capital taxes. Some people call for CGT to be raised. They argue that it is unfair that gains are taxed at lower rates than earned income and that the main beneficiaries of this are found at the top of the income distribution. Others call for CGT rates to be cut. They argue that this will boost investment and growth. There is truth in both arguments. What both miss is the tax base. The tax base has a range of problems including – but not only – that inflationary gains are taxed. With a reformed tax base, investment incentives would be improved. Rates could be increased without damaging investment incentives. This is a case where you can’t understand how a tax is affecting people and businesses unless you look beyond tax rates.
With renewed debate about taxing wealth, where do you think the UK tax system most needs reform?
There is huge scope to reform the taxation of investment incomes and gains. We should start there.
Removing uplift of CGT at death is a contender for what I would do if I could make only one specific change. If choosing an area of the tax system to fix, I would start with how we tax different ways of earning income. This is basically about the interplay of income tax, NICs, corporation tax and CGT. Having spent much of my career working on this, I’m convinced that we could create a system that is both fairer and better for growth. Such a system would have stronger incentives to invest and higher taxes in cases where people get very large returns from their wealth. This would require changes to all of the taxes listed above. Policymakers have made plenty of changes to these taxes in recent years but seemingly without a clear end goal. We need greater recognition that there is no way to fix the tax system that doesn’t involve acknowledging that it’s a system in which taxes need to fit together sensibly.
You might not know this about me but...
I have two small children and adore being a mum. If I’m not thinking about fiscal policy, you’ll probably find me building a Duplo zoo or out on an adventure with my kids.