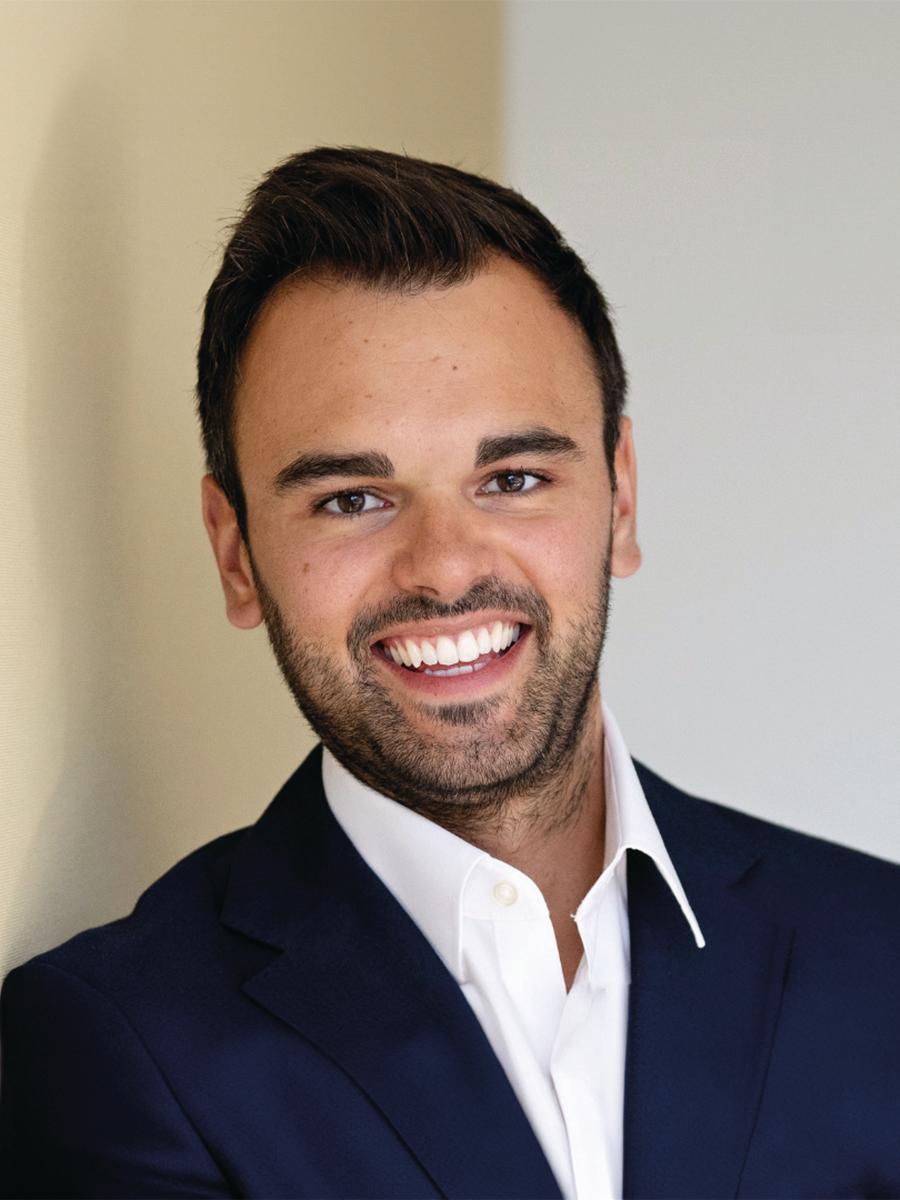
One minute with Tom Margesson, Partner at Travers Smith.
What’s keeping you busy at work?
I focus on advising private capital managers and their investment funds. Recently that’s resulted in lots of work on evergreen fund structures (open-ended fund structures designed to attract non-professional investors), investments into fund managers (as managers look to scale and realise their own value) and secondaries transactions (as funds hunt for alternative ways to realise their investments). From time to time, case law intrudes, and this summer has been one of those occasions, with a slew of cases on the taxation of LLPs. Many private capital managers are established in the UK as LLPs, and so we have been helping them navigate these developments and the associated HMRC enquiries.
What do you know now that you wish you’d known at the start of your career?
Firstly, as I always tell our new tax trainees, technical expertise is about method more than knowledge. Even as a partner, I still encounter areas of tax law for the first time, but it is your analytical method (practised over many years) that is the foundation of technical expertise.
Second, private practice is fundamentally about relationships, and it’s never too early to start building those. Many of my best client relationships were forged when I was a relatively junior lawyer.
Third, you need to have gears as a tax lawyer. Sometimes there are periods of client demand where you need to work in ‘fifth gear’, but for most people, doing that every day quickly becomes unsustainable. Part of the challenge of building a long-term career in tax is knowing when and how to move back down the gears.
If you could make one change to tax, what would it be?
I would change the incentive our VAT rules give to UK fund managers to establish foreign, rather than UK, private funds. The domestic fund management exemption is narrow and does not include supplies to most private funds. Managers typically cannot charge them VAT because most funds do not make taxable supplies and so cannot recover it; therefore, the VAT cost would stick and be a drag on returns. Addressing this by grouping the fund with the manager entity has the drawback of often reducing the management group’s own input VAT recovery rate. Many managers therefore use a non-UK fund vehicle, as supplies to it are outside the scope but with a right to recovery. Effectively, we are paying UK managers to establish foreign funds.
There is no easy answer to this. We do not want a solution that brings parity by worsening the position of supplies to non-UK funds (e.g. VAT exemption). The answer that I, and the wider industry, favour is zero-rating, but this was rejected on cost grounds by the last Conservative government. It is hoped that a future government looking for levers to improve UK growth might revisit this area.
What’s topical in your world?
The UK’s decision to tax carried interest under the income tax framework continues to raise two topical issues. First, non-UK resident carryholders performing services in the UK are now drawn into the UK tax net. This can cause double taxation due to mismatches in the double tax treaty treatment of carry receipts between jurisdictions. There are no real solutions save for minimising UK travel (not a great outcome for UK plc). Second, tax on carry will be accounted for under the payment on account system. Due to the lumpy and unpredictable nature of carry receipts, this may create significant cash flow difficulties. It is hoped that the consultation on the payment on account regime could lead to some ameliorating reforms.
You might not know this about me but...
I grew up on a farm in the West Country, and until starting at Travers Smith, still spent my summers working the harvest. It gave me a strong connection to the natural world, and I’m still at my happiest spending time with family in the countryside.