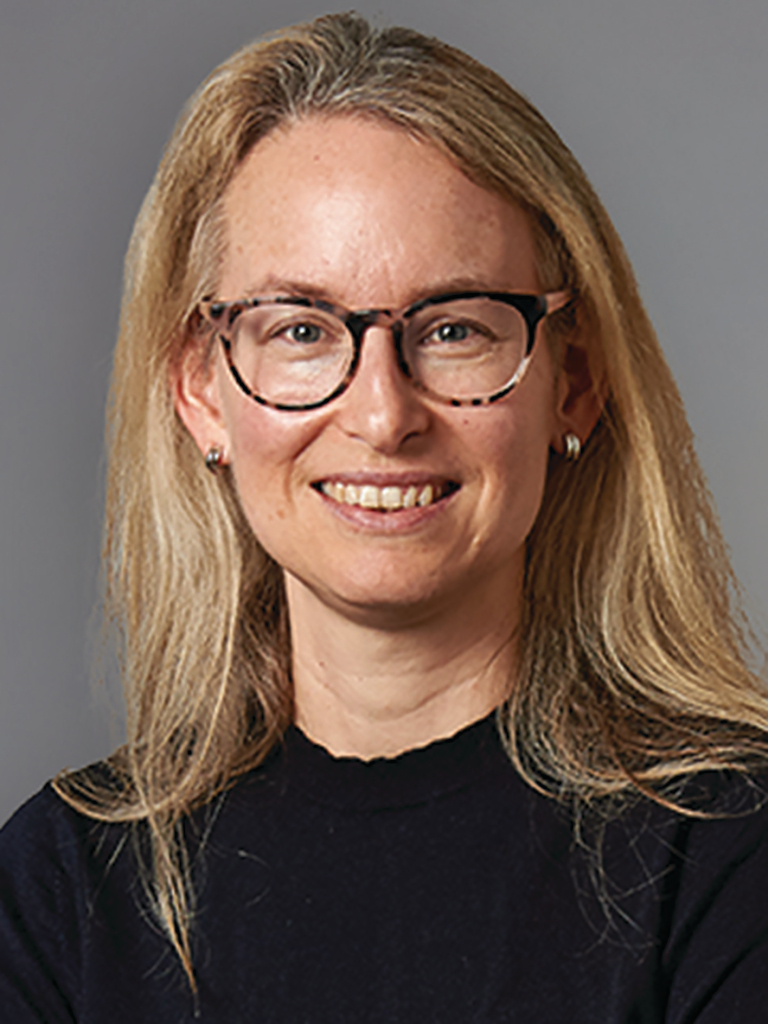
One minute with Laura Gould, Partner at Shoosmiths.
What’s keeping you busy at work?
I’m balancing a busy mix of M&A, private equity and incentives work. From helping a private equity client on an auction bid, advising management on a transaction, supporting overseas clients doing business in the UK or implementing EMI schemes for an early-stage company, no two days are quite the same, which I love.
What do you know now that you wish you’d known at the start of your career?
I wish I’d known that careers are rarely linear. There will be periods when your career takes centre stage and times when your family does. I’d also tell my younger self not to assume good work speaks for itself. You are your own best advocate, so don’t be afraid to let people know about your achievements and the value you bring.
If you could make one change to tax, what would it be?
The transactions I advise on commonly include some form of earn-out, so greater certainty in this area would be welcome, particularly as we are seeing increasingly bespoke commercial arrangements. HMRC’s guidance on when an earn-out should be treated as capital rather than income at ERSM110940 relies on factors that do not always neatly align with modern deal structures. While the guidance has evolved over time, its underlying framework remains largely unchanged from publication in 2016.
Important features commonly encountered in practice, including good and bad leaver provisions and the treatment of a leaver’s earn-out entitlement, are not specifically addressed. Nor does the guidance provide examples of what HMRC would regard as a ‘reasonable requirement’ for a seller to remain employed in order to protect the value of the business being sold.
Inevitably, this is a highly fact-sensitive area and a bright-line test is unlikely to be appropriate. However, additional examples and greater clarity around how the existing principles apply to common commercial arrangements would be helpful. Advisers are often left assessing relative risk and negotiating protections late in the transaction process.
With reports over the summer of increased HMRC scrutiny in this area, the tax treatment of earn-outs seems likely to remain a key consideration in many deals. More detailed, practical guidance could improve certainty, reduce transaction costs and disputes, and help ensure the guidance continues to reflect the way transactions are structured in practice.
What’s topical in your world?
With the Budget now less than two months away, much of the conversation is about what it might bring. In something of a re-run of 2024, complete with another half-term Budget, the prospect of further tax changes is already shaping behaviour. With continued pressure on the public finances and a new Prime Minister, many clients are assessing whether to accelerate transactions ahead of the Budget, rather than risk the rules changing mid-deal.
Alongside advising clients, I’m participating in feedback on several HMRC consultations. I’m particularly interested in the proposed reforms to withholding tax on interest paid to overseas lenders and the modernisation of the distributions regime. Both have the potential to significantly affect the way clients structure their arrangements.
Finally, you might not know this about me but…
Having grown up in a football-loving family, my first career ambition was to be a football journalist. These days, football is still a big part of family life. My husband and son are passionate fans, albeit my daughter is a little harder to convince. And yes, we found ourselves up at 2am to watch Mexico v England during the recent World Cup!
One minute with Laura Gould, Partner at Shoosmiths.
What’s keeping you busy at work?
I’m balancing a busy mix of M&A, private equity and incentives work. From helping a private equity client on an auction bid, advising management on a transaction, supporting overseas clients doing business in the UK or implementing EMI schemes for an early-stage company, no two days are quite the same, which I love.
What do you know now that you wish you’d known at the start of your career?
I wish I’d known that careers are rarely linear. There will be periods when your career takes centre stage and times when your family does. I’d also tell my younger self not to assume good work speaks for itself. You are your own best advocate, so don’t be afraid to let people know about your achievements and the value you bring.
If you could make one change to tax, what would it be?
The transactions I advise on commonly include some form of earn-out, so greater certainty in this area would be welcome, particularly as we are seeing increasingly bespoke commercial arrangements. HMRC’s guidance on when an earn-out should be treated as capital rather than income at ERSM110940 relies on factors that do not always neatly align with modern deal structures. While the guidance has evolved over time, its underlying framework remains largely unchanged from publication in 2016.
Important features commonly encountered in practice, including good and bad leaver provisions and the treatment of a leaver’s earn-out entitlement, are not specifically addressed. Nor does the guidance provide examples of what HMRC would regard as a ‘reasonable requirement’ for a seller to remain employed in order to protect the value of the business being sold.
Inevitably, this is a highly fact-sensitive area and a bright-line test is unlikely to be appropriate. However, additional examples and greater clarity around how the existing principles apply to common commercial arrangements would be helpful. Advisers are often left assessing relative risk and negotiating protections late in the transaction process.
With reports over the summer of increased HMRC scrutiny in this area, the tax treatment of earn-outs seems likely to remain a key consideration in many deals. More detailed, practical guidance could improve certainty, reduce transaction costs and disputes, and help ensure the guidance continues to reflect the way transactions are structured in practice.
What’s topical in your world?
With the Budget now less than two months away, much of the conversation is about what it might bring. In something of a re-run of 2024, complete with another half-term Budget, the prospect of further tax changes is already shaping behaviour. With continued pressure on the public finances and a new Prime Minister, many clients are assessing whether to accelerate transactions ahead of the Budget, rather than risk the rules changing mid-deal.
Alongside advising clients, I’m participating in feedback on several HMRC consultations. I’m particularly interested in the proposed reforms to withholding tax on interest paid to overseas lenders and the modernisation of the distributions regime. Both have the potential to significantly affect the way clients structure their arrangements.
Finally, you might not know this about me but…
Having grown up in a football-loving family, my first career ambition was to be a football journalist. These days, football is still a big part of family life. My husband and son are passionate fans, albeit my daughter is a little harder to convince. And yes, we found ourselves up at 2am to watch Mexico v England during the recent World Cup!